



Choosing how to pay for a car, equipment, or another major purchase can be confusing. In house financing and bank loans are two common options, but they work in different ways.
With in-house financing, the seller or dealership may arrange the financing directly. With a bank loan, a separate financial institution provides the money and sets the loan terms.
Understanding the differences in approval, interest rates, credit requirements, repayment terms, fees, and flexibility can help you compare your options before signing an agreement.
What Is In-House Financing?
In-house financing is a financing arrangement where the seller or dealership provides or manages the financing instead of sending the customer to an outside bank or lender. It is often used by car dealerships, furniture stores, equipment sellers, and other businesses.
For example, suppose you want to buy a used car. Instead of applying for a traditional auto loan from a bank, a dealership may offer its own financing program. You make payments directly to the dealership or its financing company according to the contract.
In-house financing may be particularly attractive to buyers who have limited credit history, lower credit scores, or difficulty getting traditional financing. However, easier approval can sometimes come with higher costs.
For general background on borrowing and credit, see Finance and Wikipedia’s overview of loans.
What Is a Bank Loan?
A bank loan is money borrowed from a bank or other financial institution that is repaid over an agreed period, usually with interest.
For example, you could apply to a bank for an auto loan before visiting a dealership. If approved, the bank provides financing for the vehicle, and you repay the bank through scheduled monthly payments.
Bank loans commonly involve:
- Credit checks
- Proof of income
- Debt-to-income assessment
- Interest rates
- Loan terms
- Monthly payments
- Possible fees
- Collateral requirements for some loans
The exact requirements depend on the lender, loan type, borrower, and credit profile.
Why Is In-House Financing vs Bank Loans Important?
The choice matters because the financing method can affect the total amount you pay, not just your monthly payment.
A loan with a lower monthly payment may have a longer repayment period and higher total interest. Likewise, a financing option with quick approval may carry a higher interest rate.
When comparing in-house financing with a bank loan, look beyond the payment amount. Consider:
- Annual percentage rate (APR)
- Total interest
- Loan duration
- Down payment
- Processing fees
- Late-payment charges
- Prepayment rules
- Credit requirements
- Total repayment amount
A simple comparison of the complete loan costs can prevent unpleasant surprises later.
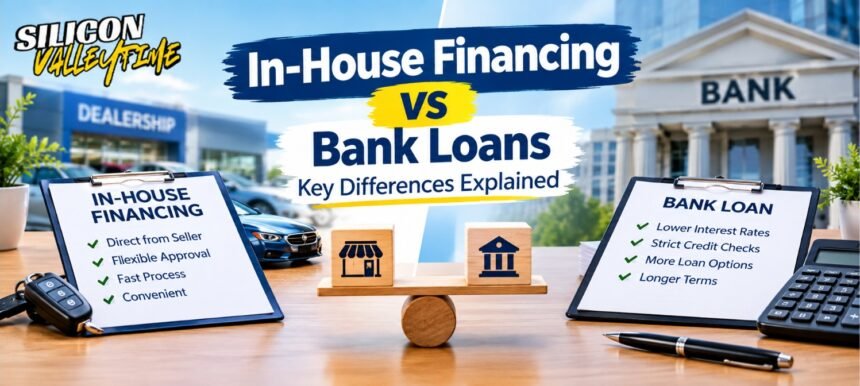
In-House Financing vs Bank Loans: Key Differences
The biggest differences usually involve the lender, approval process, rates, and borrower requirements.
| Feature | In-House Financing | Bank Loan |
| Lender | Seller/dealer or affiliated lender | Bank or financial institution |
| Application | Often handled at the point of sale | Usually separate application |
| Approval | May be more flexible | Often stricter |
| Credit requirements | Can be more flexible | Usually credit-based |
| Interest rate | May be higher | May be lower for qualified borrowers |
| Convenience | Often fast and convenient | May require more paperwork |
| Loan comparison | Limited to available program | More lenders may be available |
| Payment recipient | Seller/financing company | Bank/lender |
| Best fit | Buyers seeking convenience or flexible approval | Qualified borrowers seeking competitive terms |
These are general differences. Actual terms vary by lender and financing contract.
Key Benefits of In-House Financing
1. Easier Application Process
One major attraction of in-house financing is convenience. The buyer may be able to complete the purchase and financing process in one place.
This can save time compared with applying separately for a bank loan.
2. Flexible Credit Requirements
Some in-house lenders work with customers who have limited or damaged credit histories.
However, flexible approval does not automatically mean affordable financing. Always check the interest rate and total repayment cost.
3. Faster Decisions
A dealership or seller may make financing decisions quickly, especially when its process is designed around immediate purchases.
This can be useful when a buyer needs the product without a lengthy lending process.
4. Convenient One-Stop Purchase
The customer can sometimes choose the product, arrange financing, complete paperwork, and start repayment through the same business.
Potential Drawbacks of In-House Financing
In-house financing can also have disadvantages.
Higher Interest Rates
Some in-house financing programs may charge higher rates than traditional loans, particularly when they serve borrowers with higher credit risk.
Limited Choices
With a bank loan, you may compare offers from several lenders. An in-house program may give you fewer financing options.
Higher Total Cost
A convenient loan can still be expensive if the APR, fees, or repayment period are high.
Always compare the total amount payable rather than looking only at the monthly payment.
Benefits of Bank Loans
Bank financing has several potential advantages for qualified borrowers.
Competitive Interest Rates
Borrowers with strong credit and stable finances may qualify for competitive rates.
More Loan Options
Banks may offer different repayment periods and loan structures, allowing borrowers to compare financing choices.
Clear Lending Process
Banks generally provide detailed loan disclosures showing the rate, payment schedule, fees, and repayment terms.
Opportunity to Shop for Financing
You can often seek loan approval before making a purchase. This can help you understand your budget before negotiating with a seller.
How to Choose Between In-House Financing and a Bank Loan
Choosing between these options starts with your financial situation.
Step 1: Check Your Credit
Review your credit report and understand your approximate credit position. Better credit may give you access to more financing choices.
Step 2: Calculate Your Budget
Decide how much you can comfortably afford each month without putting pressure on your other expenses.
Step 3: Compare APRs
Don’t compare loans based only on monthly payments. Look at the APR and total repayment amount.
Step 4: Review All Fees
Ask about:
- Application fees
- Documentation fees
- Late fees
- Early repayment charges
- Dealer or administrative charges
Step 5: Compare Loan Terms
A longer loan term may reduce the monthly payment but can increase the amount of interest paid over time.
Step 6: Read the Contract
Before signing, make sure you understand the payment schedule, interest rate, penalties, collateral requirements, and other conditions.
A Simple Example
Imagine two buyers want the same $20,000 vehicle.
Buyer A chooses in-house financing because approval is quick and convenient. The dealer accepts the application despite a limited credit history.
Buyer B has stronger credit and applies for a bank loan. The bank offers a lower interest rate but requires more documentation.
Buyer A may benefit from easier approval, while Buyer B may benefit from a lower borrowing cost.
This example shows why there is no single financing method that works for everyone. The right comparison depends on the actual terms offered.
FAQs About In-House Financing vs Bank Loans
Is in-house financing better than a bank loan?
Neither option is automatically better for every borrower. Compare the APR, fees, loan term, monthly payment, and total repayment amount before deciding.
Is in-house financing easier to get?
It can be easier to qualify for in some situations, particularly for borrowers with limited or poor credit. However, approval requirements vary between businesses and lenders.
Does in-house financing affect your credit?
It can. Depending on the lender and reporting practices, payments may be reported to credit bureaus. Ask the financing company whether it reports payment activity before signing.
Can I get in-house financing with bad credit?
Some businesses offer financing programs designed for borrowers with challenging credit histories. However, these loans may have higher interest rates or additional requirements.
Do bank loans have lower interest rates?
They can, particularly for borrowers with strong credit and stable income. But rates vary by lender, loan type, market conditions, and borrower profile.
Should I compare total cost or monthly payment?
Compare total cost first. A low monthly payment can result from a longer loan term, which may increase the total interest paid.
Can I negotiate in-house financing terms?
Some sellers may have flexibility, but this depends on the business and financing provider. Ask whether the interest rate, down payment, fees, or repayment term can be changed.
Conclusion
In-house financing and bank loans serve different borrowing needs. In-house financing can provide convenience, faster processing, and potentially more flexible approval. Bank loans may provide broader choices and competitive rates for qualified borrowers.
Before choosing either option, compare the APR, total repayment cost, fees, loan duration, credit requirements, and payment terms.
The smartest approach is not simply choosing the loan with the smallest monthly payment. Instead, understand the complete agreement and choose financing that fits your budget and financial circumstances